Investments & Capital Markets
Raising capital on the Tel Aviv Stock Exchange, in the United States and beyond, and the ongoing obligations that follow — for issuers, investors and placement agents.
The firm advises companies raising capital in two markets at once, and the investors and placement agents on the other side of those transactions. Much of this work involves Israeli issuers listed or listing in the United States, where the Israeli law questions have to be answered by Israeli counsel.
The firm's founder has represented issuers and underwriters in numerous listings, public offerings and other capital markets transactions on the Tel Aviv Stock Exchange and in the U.S. capital markets, and has served as general counsel to and as a director of publicly listed companies.
What we handle
Who we act for
Issuers, whether Israeli companies listing abroad or foreign companies with Israeli operations. Investors and funds taking positions in Israeli issuers. Placement agents and underwriters who need Israeli counsel on the other side of a transaction. And holders of restricted securities who need an opinion before they can sell.
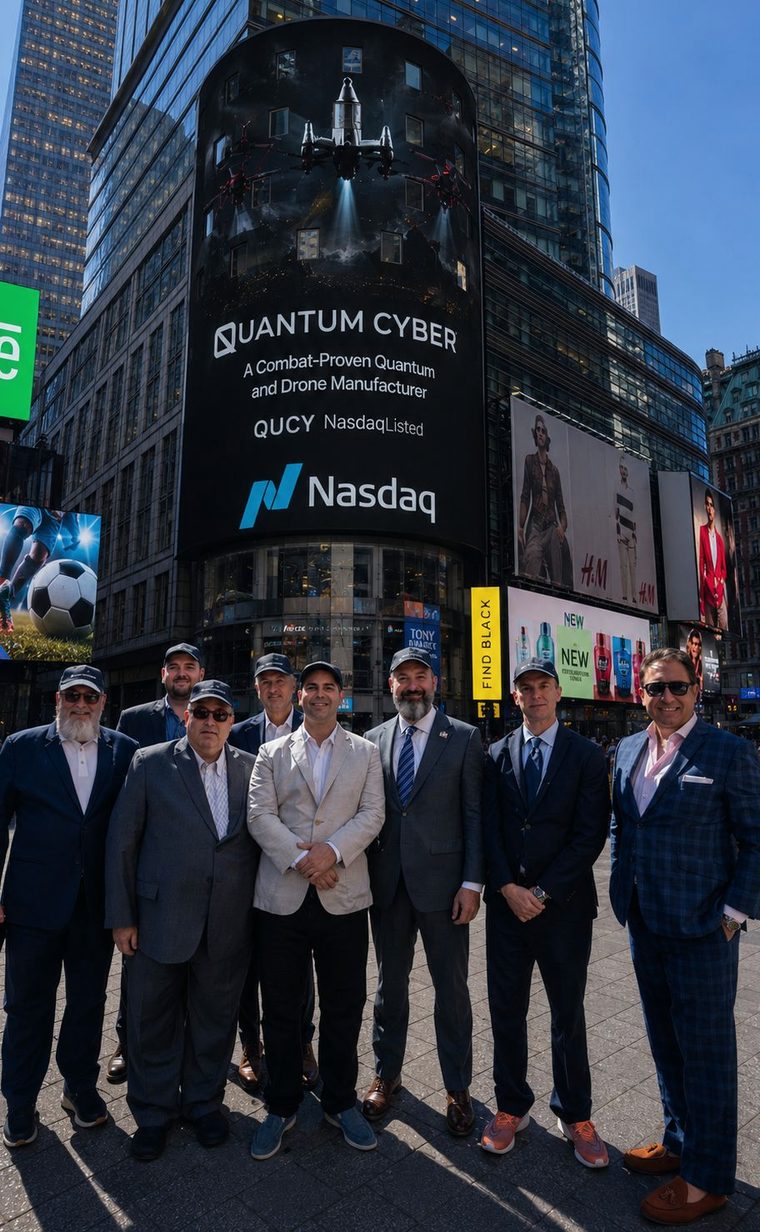
Not every client is Israeli. The firm also acts on listings where the company is incorporated in one country, trades in a second and runs its business in a third — a Dutch corporation with a United States business listed on Nasdaq, for instance. The questions are the same ones, and so is the discipline of keeping two or three sets of rules answered at once.
Life sciences and health-tech
A substantial part of this work is for Israeli life science, biotechnology and medical device companies raising money outside Israel. It is one of the sectors where Israeli companies most often outgrow the domestic market for capital, and where the investors, the listing venue and the regulator sit in another country while the company, its research and its board remain here.
Three of the companies in the firm’s selected representations are in this sector — a clinical-stage pharmaceutical company, a biopharmaceutical company and a medical device company, each listed in the United States as well as in Tel Aviv.
The firm exhibits at MIXiii, the life science and health-tech week convened by IATI in Jerusalem, among the investors, exchanges and advisers that Israeli health-tech companies deal with when they raise capital abroad.
Where companies list
Nasdaq and the Tel Aviv Stock Exchange are the routes most Israeli issuers take, and dual listing between them is well-trodden ground for this firm. They are not the only options: the Canadian markets actively court Israeli issuers, and the Canadian Securities Exchange was itself an exhibitor at MIXiii in Jerusalem in 2026.
The right venue depends on the size of the raise, the sector, the shareholder base and how much ongoing reporting the company can carry. It is a decision worth taking with counsel before it is taken with a banker.
A notable matter
A company removed from Nasdaq has lost the thing it went public for. Reversing that is uncommon: the exchange has wide discretion, the route of challenge runs through the exchange’s own hearing bodies and then to the Securities and Exchange Commission, and the company is usually running short of money and patience at the same time.
Avraham S. Ben-Tzvi acted as counsel to FiEE, Inc. — formerly Minim, Inc. — and sat on its board through the challenge to the company’s delisting, including proceedings before the Commission. The strategy was his. The matter was resolved and trading in the company’s shares was reinitiated on Nasdaq.
While that was running, Nasdaq filed a proposed rule change with the Commission to codify the standards of review governing appeals before its Listing and Hearing Review Council — the very standards in issue. The proposal drew exactly one public comment letter, filed by Avraham S. Ben-Tzvi in August 2024 (SR-NASDAQ-2024-037). Nasdaq withdrew the proposal.
Nasdaq has since removed Israeli issuers on public-interest grounds, and is likely to do so again. An issuer that understands the exposure early has options that an issuer reacting to a determination letter does not.
Prior results do not guarantee a similar outcome.
How we work
- Early involvement, because structure is cheaper to fix before a deal is papered.
- Coordination with U.S. counsel, auditors and transfer agents as a matter of routine.
- Documents and opinions delivered to the standard the receiving institution expects.
- Plain advice on what a filing obligation actually requires, and by when.
Related practices
This practice runs regularly alongside the firm’s work in Corporate, Commercial and Regulatory, Cross-Border Opinions and Foreign Law, Contracts, Litigation.